Keys, Tenants and Tax Returns: A First-Time Landlord's Guide to Getting the Paperwork Right
Photo: N Chadwick , CC BY-SA 2.0, via Wikimedia Commons
Receiving the keys to a let property — whether it's a former home, an inherited flat, or a deliberate investment — marks the beginning of a new set of responsibilities. Some are obvious: finding tenants, arranging deposits, keeping the boiler serviced. Others are less visible but no less important, and chief among them is the question of tax.
The good news is that becoming a landlord for the first time is more manageable than it first appears. The rules are well established, the paperwork is straightforward once you understand what HMRC expects, and a little early organisation prevents most of the common pitfalls. This guide walks through the essentials.
Do You Even Need to Tell HMRC?
Not every landlord must complete a Self Assessment return. If your rental income — before expenses — amounts to £2,500 or less in the tax year, you may be able to report it simply by contacting HMRC or through your PAYE tax code, depending on your circumstances.
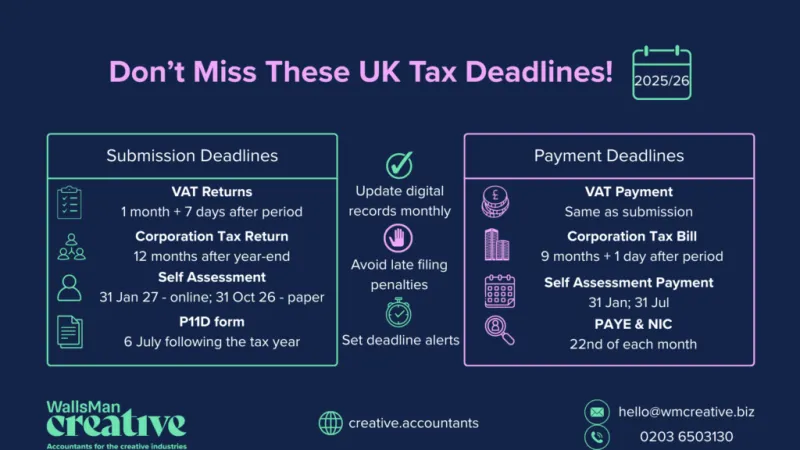
Once gross rental income exceeds £2,500, or if you need to deduct expenses and your profit exceeds the £1,000 property income allowance, a Self Assessment return becomes necessary. Registration deadlines matter: you must register by 5 October following the end of the tax year in which the income arose. Miss that date and you risk penalties, even if no tax is ultimately due.
The Property Income Allowance: A Modest but Useful Relief
The £1,000 property income allowance is worth understanding from the outset. If your gross rental receipts are below £1,000 for the year, the income is effectively tax-free and needs no declaration. If receipts exceed £1,000, you face a choice: claim the allowance instead of actual expenses, or deduct your genuine costs in full.
For most landlords with meaningful expenditure — and most have some — deducting actual expenses produces the better result. The allowance tends to suit those with minimal costs, such as someone renting a single room informally.
What You Can Claim: The Landlord's Expense Toolkit
Allowable expenses are the backbone of rental tax reporting, and they go beyond what many first-time landlords expect. The principal categories include:
- Letting agent fees and management charges — a common and frequently overlooked cost
- Repairs and maintenance — fixing a broken boiler, repainting between tenancies, replacing a damaged door
- Insurance — buildings and, where relevant, landlord-specific policies
- Council tax, utility bills and ground rent — where you, not the tenant, bear them
- Accountancy fees — including the cost of professional advice such as this
A crucial distinction lies between repairs and improvements. Repairing an existing feature — replacing like with like — is deductible. Upgrading beyond the original standard, such as installing an extension or fitting a higher-specification kitchen, is capital expenditure. Capital costs are not deducted from income; instead, they may reduce a Capital Gains Tax bill when you eventually sell the property. Conflating the two is one of the most frequent errors we see.
The Section 24 Wrinkle
Since 2020, individual landlords can no longer deduct mortgage interest in full from rental income. Instead, they receive a tax credit worth 20% of their finance costs. For higher-rate taxpayers this can significantly increase the tax owed on rental profits, and it has prompted many to reconsider whether owning property personally still suits their circumstances. It is worth understanding your position before the first tax return, not after.
How It All Fits into Self Assessment
Rental income is reported using the property pages (SA105) alongside the main return. You will record your total income and expenses under the accruals basis — meaning income and costs are matched to the period they relate to, not when money changes hands.
Keep records methodically: tenancy agreements, invoices, bank statements, and a simple income and expenditure log. HMRC expects records to be retained for at least five years after the 31 January submission deadline. Digital bookkeeping software makes this painless, and since Making Tax Digital is gradually extending to income tax, building the habit now is a sensible investment.
A Final Word of Reassurance
A first tenancy is, in effect, the start of a small enterprise. Treated with the same organisation you would apply to any business — records kept current, deadlines diarised, advice sought before decisions rather than after — the tax side becomes routine.
If you are letting a property for the first time and would prefer not to navigate the details alone, we would be glad to help. A short conversation early on can save considerable cost and worry later.